
Why Every Forex Broker Needs a Dedicated PSP Payment Solution
General-purpose payment providers often decline forex and CFD businesses, and those that accept them can change their minds. A dedicated PSP payment solution built around brokers gives you more reliable funding, better reconciliation and a plan for when a route fails.
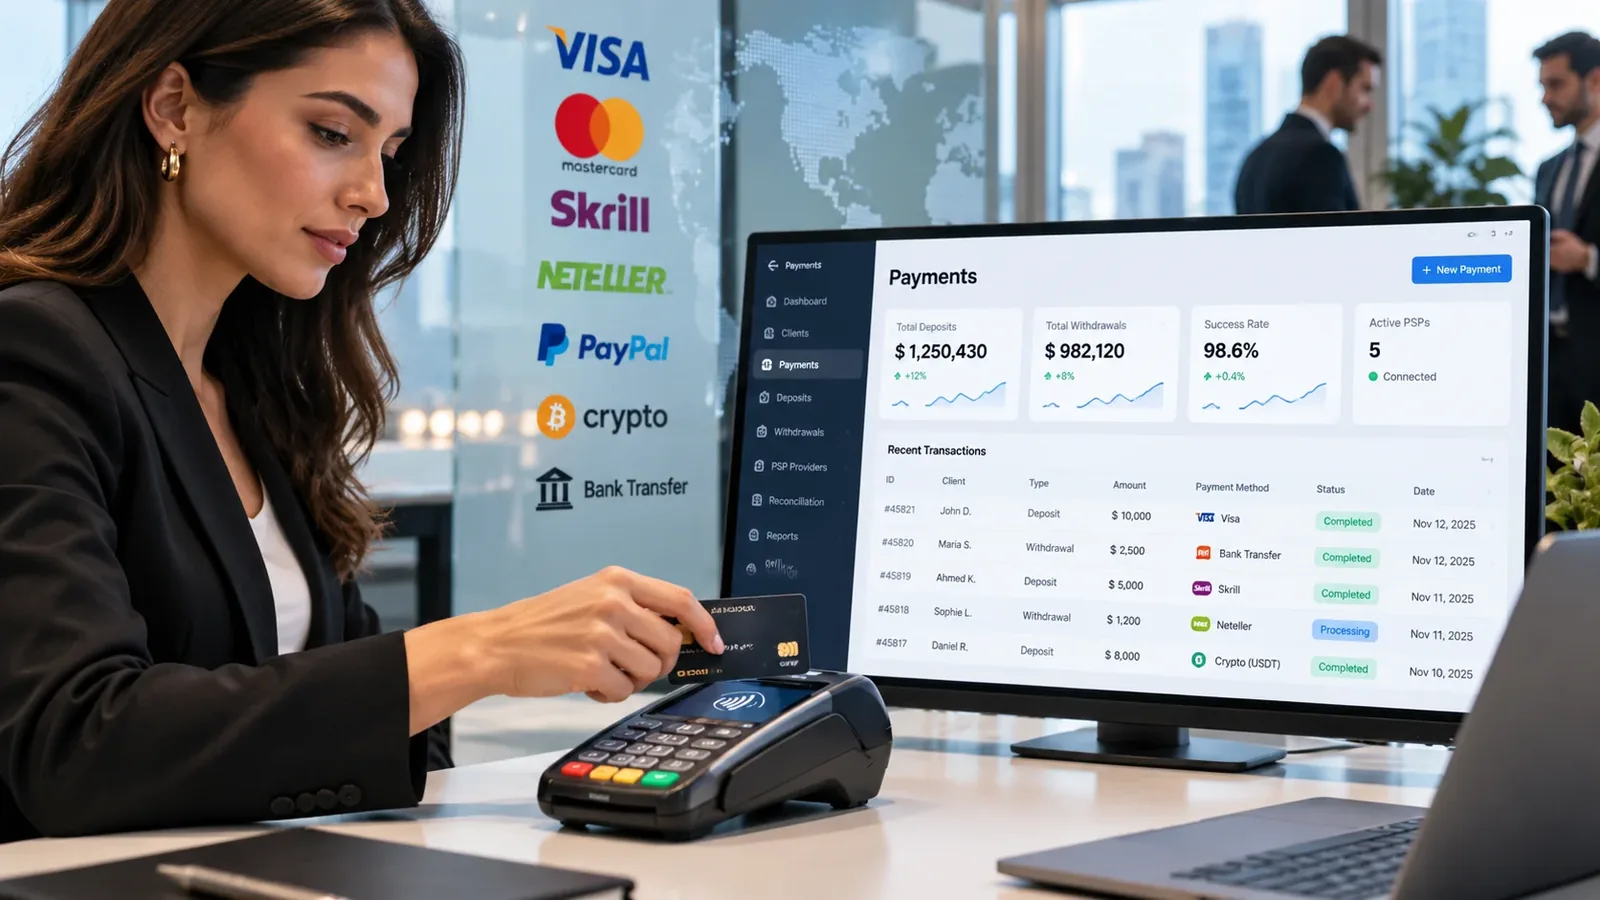
Why general providers often do not fit
Many mainstream payment providers restrict or refuse forex and CFD flow, because of regulatory and chargeback risk. Even when they accept you, terms can change.
Providers that understand the industry ask the right questions up front and build their service around broker needs.
Funding is where a lead becomes a client
Deposits and withdrawals decide how clients feel about a broker. Slow, unclear or failed payments cost clients quickly. A dedicated solution gives you more payment methods, clearer statuses and faster support.
Reconciliation and records
Every payment should match a client account and appear in the CRM with a clear status. Automated reconciliation reduces manual work and mistakes. Read how this connects to the CRM in our payment gateway integration guide.
Fraud and risk controls
Look for transaction monitoring, authentication where relevant, chargeback tools and the ability to hold unusual payments for manual review. You stay responsible for your own compliance, so choose controls that fit your procedures.
Continuity and fallback
Do not rely on a single provider. Plan a second route and agree how clients will be told if one is unavailable. See our PSP guide for terms to compare, and our liquidity provider guide for the other half of the money flow.
Questions to ask a payment provider
- Do you accept forex and CFD businesses, and in which jurisdictions?
- What are your fees, reserves, limits and settlement times?
- How are chargebacks and disputes handled, and who bears the cost?
- What onboarding documents do you need from us?
- How do callbacks, retries and reconciliation reports work?
- What notice do you give before changing terms?
Ask for the answers in writing and compare providers in one table.
Planning the rollout
Start with a small number of reliable methods for the regions you serve, test every flow with real small payments, and train support on how to explain statuses and delays to clients. Add methods gradually as volumes grow.
Keep a record of provider approvals, limits and review dates so renewals and changes never surprise you. Plan the second provider before you need it.
Payment methods compared
Different funding methods suit different clients and carry different trade-offs. The table is a framework for your own research. Availability, fees and rules depend on provider, country and time.
| Method | Client convenience | Typical considerations |
|---|---|---|
| Card payments | High | Approval rates, chargebacks, provider acceptance of forex |
| Bank transfer | Medium | Speed, reconciliation, local details |
| Local payment methods | High in specific markets | Coverage, settlement terms |
| E-wallets | High for some audiences | Fees, withdrawal rules, provider appetite |
| Crypto payments | Medium | Compliance, volatility handling, conversion |
Start with the methods your target clients actually use, then add others as volume justifies the effort.
A worked example of a declined deposit
A new client tries to fund an account by card and is declined. The client contacts support, who see only the message "transaction failed". The client tries again, fails again and abandons registration.
A better setup shows support the decline reason where the provider allows it, offers the client an alternative method in the same screen and records the attempt for review. After a month the team studies the decline reasons, finds that a particular card type is often refused, and adds a bank transfer option to the funding page. The change comes from data and treats a decline as information, not as lost business.
Reconciliation: the unglamorous essential
Every payment should reconcile across three places: the payment provider, your CRM and the trading server. Differences are inevitable, so build a daily routine to find them.
Define who owns reconciliation, what tolerance is acceptable and how exceptions are resolved. Keep an audit trail of corrections. Without reconciliation, small errors accumulate into large ones and become painful during audits and partner reviews.
Fraud and risk controls
- Verify identity before enabling withdrawals.
- Withdraw to the same method used to fund where appropriate.
- Monitor unusual patterns such as rapid deposits and withdrawals.
- Set limits that reflect client profile and risk.
- Keep records for compliance and disputes.
Apply controls consistently and explain them to clients in plain language. See our CRM security guide for related practices.
Continuity and fallback
A single provider is a single point of failure. Plan at least one fallback for your most important funding method, and know how to switch quickly. Test the fallback occasionally, not only when something breaks.
Read our payment provider page and the gateway integration page for solution details.
Mistakes in payment planning
- Waiting for provider approval before planning the client journey.
- Offering too many methods at launch and supporting none of them well.
- Treating declines as lost business instead of data.
- Skipping reconciliation until volumes grow.
- Having no fallback if the main provider pauses the account.
A smaller set of well-tested methods almost always beats a long list that nobody has checked.
A first-90-days payments plan
Month one: apply to providers, prepare documents and design the funding page. Month two: test with small amounts, reconcile daily and tune messages for declines. Month three: review approval rates and withdrawal times, add a second method where the data shows demand and agree a fallback with the provider.
Documents providers commonly ask for
- Company registration and ownership details.
- Business plan and expected volumes.
- Licence or regulatory position, where applicable.
- Website with legal pages and risk warnings.
- Compliance policies, including AML and KYC.
- Banking details and source of funds.
Prepare the pack before applying, and keep it consistent. Providers notice contradictions and may delay or decline.
Frequently asked questions
What is a forex PSP?
A payment service provider that processes client deposits and withdrawals for a brokerage, ideally with an understanding of forex requirements.
Why is it hard to find a payment provider for forex?
Some providers treat the sector as higher risk and apply stricter checks. Prepare a clear business plan and compliance documents.
What payment methods should I offer?
Those your target clients use. Start with a few and expand with demand.
How do I handle chargebacks?
Keep strong records, communicate clearly with clients and follow the provider’s dispute process. Monitor rates and address causes.